How Mastercard Works at Online Casinos in Ireland

Home Business Magazine Online

A card you already carry is the simplest way to fund an account. In Ireland, that card option is very often a Mastercard, sitting in a wallet or a phone. Mastercard casinos lean on that reach, so a deposit takes only a few quick taps. The brand runs sharp fraud checks behind the scenes, and a stray charge rarely gets through. This article walks through the deposit, the payout side, how it compares, and the costs. Read it through, and Mastercard will feel straightforward from the first euro.

How Common Is Mastercard at Irish Casinos

Mastercard options turn up at nearly every casino that serves Ireland, right next to Visa. That wide reach is the first reason players pick it, since you rarely hit a site that says no. The card already sits in your wallet, so there is no new app and no fresh sign-up. So convenience does most of the selling here.

Acceptance also runs across the phone, since most Irish Mastercards link to Apple Pay or Google Pay. That gives you two ways to use the same card, by number or by tapping. A deposit clears the moment your bank approves it, and the games open at once. So Mastercard fits both the careful typist and the one-tap player.

Mastercard on Mobile

Most Irish Mastercards now live on the phone as well as in the wallet. Through Apple Pay or Google Pay, the same card pays with a tap and a Face ID scan. So you can fund a casino without typing a single digit at the cashier.

The token behind a mobile tap also hides the card number from the site. That adds a layer of cover that a typed payment does not have. The deposit still lands instantly, and the win still returns to the card. So the phone gives you the quickest and most private way to use Mastercard.

How to Make a Mastercard Deposit

A Mastercard deposit takes under a minute. Follow these steps:

  1. Open the cashier. Log in to the casino and go to the deposit page.
  2. Choose Mastercard. Pick the card option from the list of methods.
  3. Enter the details. Type the card number, the expiry, and the CVV.
  4. Set the amount. Decide how much to add, within the site limits.
  5. Confirm the payment. Approve any Identity Check, and the funds land at once.

The casino saves the card after the first time, so later deposits skip the typing. You pick the stored card, confirm, and the money lands again with a tap.

The Payout Question

A common worry is whether a win can come back to the same Mastercard. At many sites, it can be done through Mastercard’s own payout rails. The money returns to the card you funded with, which keeps the trail tidy. A card payout usually takes one to three business days to show.

Some sites cannot send funds to a card, so they route the payout to your bank instead. Either way, at Mastercard casinos in Ireland, you verify the account first, and the first withdrawal then clears cleanly. So Mastercard keeps deposits instant, and the cash-out follows normal bank time. Check the cashier to see which route your site uses.

Mastercard Against Other Methods

It helps to see where Mastercard sits next to the other options Irish players use. Here you can compare them:

Method Deposit Payout Typical Limits
Mastercard Instant 1 to 3 days €10 to €5,000
PayPal Instant A few hours €10 to €5,000
Apple Pay Instant To card or bank €10 to €3,000
Revolut Instant Within hours €10 to €5,000
Crypto Instant Minutes €20 and up


Mastercard wins on reach and an instant deposit, but a wallet or crypto pays out faster. So many players at Mastercard casinos in Ireland deposit by card and cash out by a quicker route.

Costs to Keep an Eye On

Mastercard keeps casino payments simple, but a couple of costs can slip in. Keep these in mind:

  • The casino rarely charges for a Mastercard deposit, so it usually costs nothing;
  • A site that bills outside the euro can add a 2% to 3% currency cost;
  • A minimum deposit of around €10 unlocks play at most sites;
  • Daily and monthly caps vary, so check the cashier for the limits;
  • A payout to the card is free at most sites, though the bank sets the timing.

A quick read of the cashier page heads off any surprise. A euro-billing site keeps the cost near zero.

A Few Habits for Card Players

A handful of simple habits keep card play smooth and safe. Try these:

  • Verify early. Send your ID at sign-up so the first payout clears fast;
  • Match the method. Deposit and cash out the same way to skip extra checks;
  • Watch the statement. Each Mastercard payment shows up, so tracking is easy;
  • Set a cap. Use the site’s limit tools to keep a session in check;
  • Stay licensed. Play only at Irish-facing sites with a clear licence.

These cost nothing and take only a moment to set. A little care up front saves a lot later.

Conclusion

A Mastercard gives Irish players a fast, familiar way to fund a casino account. Almost every site takes it, deposits clear in seconds, and a payout follows in a day or two. The card moves money quickly, and a quick check of the costs keeps it cheap. Pick a licensed site, verify early, and Mastercard handles the rest.

The post How Mastercard Works at Online Casinos in Ireland appeared first on Home Business Magazine.

Original source: https://homebusinessmag.com/blog/locations/ireland/mastercard-works-online-casinos-ireland/

The Critical Role of Financial Advisors in Modern Ireland

Home Business Magazine Online

In an increasingly complex financial landscape, Irish citizens face a myriad of challenges when managing their wealth, planning for retirement, and securing their family’s future. From navigating the intricacies of pension regulations to understanding investment opportunities and tax obligations, the modern financial world demands expertise that extends far beyond basic budgeting. This is where financial advisors have become indispensable partners for individuals and families across modern Ireland, offering professional guidance that can make the difference between financial uncertainty and long-term prosperity.

Understanding the Irish Financial Landscape

Ireland’s financial environment has undergone significant transformation over the past two decades. The country has evolved into a sophisticated financial hub, attracting multinational corporations whilst maintaining a robust domestic economy. However, this progress has brought increased complexity for ordinary citizens attempting to manage their personal finances effectively.

The Irish taxation system, whilst designed to be fair, presents numerous intricacies that can confound even the financially literate. From Universal Social Charge (USC) to Capital Gains Tax (CGT) and the various reliefs available, understanding how to optimise one’s tax position requires specialist knowledge. Additionally, Ireland’s pension landscape—encompassing State Pensions, Personal Retirement Savings Accounts (PRSAs), and occupational pension schemes—demands careful navigation to ensure adequate retirement provision.

Financial advisors possess the expertise to interpret these complexities and translate them into actionable strategies tailored to individual circumstances. Their value lies not merely in their technical knowledge, but in their ability to contextualise financial decisions within the broader framework of a client’s life goals and aspirations.

Comprehensive Retirement Planning Support

Perhaps nowhere is the importance of financial advisors more evident than in retirement planning. The stark reality facing many Irish citizens is that the State Pension alone will not provide sufficient income to maintain their desired standard of living in retirement. According to recent studies, there is a significant pension coverage gap in Ireland, with many workers inadequately prepared for their later years.

Financial advisors in modern Ireland, like Secure Your Future play a crucial role in addressing this deficit. They conduct thorough assessments of current pension arrangements, project future income needs, and develop strategies to bridge any gaps identified. This process involves analysing existing pension contributions, recommending appropriate Additional Voluntary Contributions (AVCs), and ensuring that clients maximise available tax relief on pension investments.

Moreover, advisors help clients understand the various retirement options available when the time comes to access their pension funds. The decisions made at retirement—whether to take a lump sum, purchase an annuity, or opt for an Approved Retirement Fund (ARF)—have profound and lasting implications. Professional guidance ensures these choices align with individual circumstances, risk tolerance, and income requirements throughout retirement.

Strategic Investment Guidance

Beyond pensions, financial advisors provide invaluable assistance with broader investment strategies. The investment landscape offers numerous opportunities, from stocks and bonds to property, funds, and alternative investments. However, this variety can prove overwhelming for individuals without specialist knowledge.

A qualified financial advisor conducts detailed risk profiling to understand a client’s capacity for loss, investment timeline, and financial objectives. This assessment forms the foundation for constructing a diversified investment portfolio designed to achieve growth whilst managing risk appropriately. Advisors also provide ongoing portfolio management, making adjustments as market conditions change and as clients progress through different life stages.

Importantly, financial advisors help clients avoid common investment pitfalls. Emotional decision-making during market volatility, inadequate diversification, and chasing past performance are just some of the mistakes that can significantly erode wealth. Professional guidance provides a rational, disciplined approach that keeps clients focused on long-term objectives rather than short-term market movements.

Protection Planning and Risk Management

An often-overlooked aspect of comprehensive financial planning is protection planning. Financial advisors ensure that clients have appropriate insurance coverage to safeguard themselves and their families against unforeseen circumstances. This includes life assurance, income protection, serious illness cover, and mortgage protection insurance.

The importance of adequate protection becomes painfully apparent when tragedy strikes. Without proper coverage, families can face financial devastation in addition to emotional trauma. Financial advisors assess protection needs objectively, considering factors such as outstanding debts, dependent children, loss of income, and future financial obligations. They then recommend appropriate coverage levels and policy types, ensuring that protection is both adequate and cost-effective.

Furthermore, advisors regularly review protection arrangements as circumstances change. Marriage, children, career progression, and house purchases all impact protection requirements. Regular reviews ensure that coverage remains appropriate throughout the various stages of life.

Navigating Life Transitions Successfully

Life is punctuated by significant transitions, many of which have substantial financial implications. Whether purchasing a first home, getting married, starting a family, changing careers, or dealing with inheritance, these milestones require careful financial consideration.

Financial advisors provide essential guidance during these pivotal moments. For first-time buyers, they offer advice on mortgage options, deposit requirements, and the various government schemes available to help people onto the property ladder. For those receiving an inheritance, advisors help with tax planning, investment strategies, and ensuring that newfound wealth is managed prudently rather than squandered.

During divorce or separation, financial advisors work alongside legal professionals to help clients understand the financial implications and plan for their new circumstances. Similarly, for those starting businesses, advisors provide guidance on business structure, pension provision for the self-employed, and strategies for extracting wealth from the business tax-efficiently.

Tax Efficiency and Wealth Preservation

Taxation represents one of the most significant drags on wealth accumulation and preservation. Without proper planning, Irish taxpayers can find themselves paying substantially more tax than necessary, limiting their ability to build wealth and achieve financial goals.

Financial advisors possess detailed knowledge of the Irish tax system and available reliefs in modern Ireland. They structure financial arrangements to maximise tax efficiency, from utilising pension tax relief to understanding the nuances of Capital Acquisitions Tax (CAT) for inheritance planning. For higher earners and business owners, sophisticated tax planning can result in substantial savings over time.

Estate planning represents another critical area where financial advisors add considerable value. Ensuring that wealth passes to the next generation in the most tax-efficient manner requires careful structuring and advance planning. Advisors work with clients to develop strategies that minimise CAT liability whilst ensuring their wishes are fulfilled.

Behavioural Coaching and Accountability

Beyond technical expertise, financial advisors serve as behavioural coaches, helping clients maintain discipline and avoid counterproductive financial behaviours. Research consistently demonstrates that emotional decision-making—particularly panic selling during market downturns—significantly impairs investment returns.

Financial advisors provide the steady hand needed during turbulent times, keeping clients focused on their long-term plans rather than reacting to short-term noise. They also provide accountability, ensuring that clients follow through on financial commitments such as regular saving and pension contributions.

This behavioural dimension of financial advice, whilst less tangible than technical recommendations, often proves equally valuable in achieving successful financial outcomes. The presence of a trusted advisor can mean the difference between staying the course during difficult markets and making costly mistakes.

Conclusion: An Investment in Your Financial Future

The importance of financial advisors in modern Ireland cannot be overstated. In an increasingly complex financial world, professional guidance has transitioned from luxury to necessity for those serious about achieving their financial goals. Financial advisors bring expertise, objectivity, and discipline to financial planning, helping clients navigate challenges and capitalise on opportunities.

Whether planning for retirement, building wealth through investments, protecting loved ones, or managing life transitions, financial advisors provide the knowledge and support needed for success. Whilst there is a cost associated with professional advice, the value delivered—through improved returns, tax savings, risk management, and peace of mind—substantially exceeds this investment.

For Irish citizens seeking financial security and prosperity, engaging a qualified financial advisor represents one of the most important decisions they can make. In doing so, they gain not merely a service provider, but a long-term partner committed to helping them achieve their financial aspirations and secure their family’s future.

The post The Critical Role of Financial Advisors in Modern Ireland appeared first on Home Business Magazine.

Original source: https://homebusinessmag.com/blog/locations/ireland/critical-role-financial-advisors-modern-ireland/

Why Returning to Visit Your Old City Feels Emotionally Wrong

Home Business Magazine Online

There was a time when revisiting an old hometown carried the emotional logic of a movie ending. Familiar streets were supposed to unlock nostalgia. Former apartments were expected to glow with emotional significance. A favorite café from university years was meant to confirm that some version of the past still existed intact.

Instead, many people now return to visit your old cities and feel strangely disconnected from them. The discomfort rarely comes from architecture or weather. It comes from the disturbing realization that identity is no longer bound by physical locations as it used to be. Cities are emotional archives of a “passed away” self and revisiting these places is not quite like coming home but more like stumbling on a forgotten social account.

The Geography of Former Versions of the Self

The walk through the old neighbourhood produces a peculiar contrast between reality and memory.  Once a restaurant that seemed to be in every Instagram story is now vacant. There are only tagged photos from 2018 that remain from years of friendships that were once part of a bar. The apartment building itself becomes unfamiliar, its personality is no longer there even at apartment buildings.

Nostalgia Became Socially Complicated

The emotional tension becomes even more visible because moving has turned into its own kind of internet culture. Entire corners of social media revolve around reinvention content, moving diaries, apartment resets, and starting over in unfamiliar cities. Even moving companies like Elatemoving have become part of that modern cycle of leaving one version of life behind and building another somewhere else.

Why Familiar Places Suddenly Feel Hostile

The emotional discomfort often comes from subtle social rituals that nobody openly discusses:

  • running into people connected to abandoned versions of identity
  • realizing favorite locations were emotionally important only within a specific social era
  • noticing how much personal style, language, humor, or ambition changed over time
  • understanding that online reputation sometimes outlives real emotional connection
  • feeling unexpectedly invisible inside spaces that once felt central to daily life

These moments rarely create dramatic breakdowns. The feeling is quieter and more culturally modern than that. It resembles opening an old streaming account and discovering recommendation algorithms still trying to reconstruct a personality that disappeared years ago.

The New Anxiety Around Recognition

There’s something bizarre about going back to an old town, finding out how much people really wanted some control over how they’re recognized. In between lies the discomfort of full anonymity, while the discomfort of full recognition is reconnecting someone to a past identity that they are no longer associated with.

People’s social behaviour is becoming more and more centered on selective visibility.  Online culture encourages constant editing of the self, where older versions remain technically accessible but emotionally distant. Returning to visit your old city disrupts that carefully managed separation. Suddenly, old coworkers remember outdated ambitions. Former classmates reference forgotten habits. Even local routines begin exposing how much personality was shaped by the environment itself.

The Emotional Risk of Looking Backward

It is always interesting to see how things have changed when one encounters an old place again, and one gains a larger perspective of what is to be found in modern culture. Emotional affiliation is increasingly being achieved in short term “digital communities” rather than consistent “real-world” communities. Friendships transfer from one platform to another. Personal reinventions are public. There is a split of recognition between the virtual and real spaces.

That’s why it might feel like it’s emotionally wrong to return even when nothing bad actually happens. The city is still there but the emotional network with it is already archived and reformatted, and in some respects replaced by newer versions of the self, seeking survival elsewhere.

The post Why Returning to Visit Your Old City Feels Emotionally Wrong appeared first on Home Business Magazine.

Original source: https://homebusinessmag.com/lifestyles/travel/returning-visit-old-city-feels-emotionally-wrong/

The Side Hustle Hiding in Your Local WhatsApp Group – Without Annoying the Neighbours

From dog walks to click-and-collect runs, your neighbourhood WhatsApp group could be the easiest place to find paid side hustle work – if you do it kindly, clearly and without sounding like a pyramid seller.

During the pandemic, local WhatsApp and Facebook groups sprang up everywhere. Villages set them up. Market towns set them up. London boroughs set them up. They helped people stay connected, collect prescriptions, check in on older neighbours and look after each other when life felt uncertain.Years later, many of those groups are still going. They are where people ask to borrow ladders, look for lost cats, recommend plumbers and find someone to pop round when they are stuck at work and the dog needs letting out.

That is where a clever side hustle opportunity may be hiding.

Not in a “DM me hun” way. Not in a “I’ve discovered an amazing business opportunity” way. And absolutely not in the pyramid-selling, aloe-vera-pushing, miracle-supplement style that makes everyone silently mute the group.

This is different. This is about offering a genuine, useful local service to people who already know you, trust you and may actually need your help.

MoneyMagpie angle

Your local WhatsApp group is not just a place to advertise. It can be the bridge between “I do the odd favour for neighbours” and “I have a small, trusted local side hustle.”

The overlooked side hustle: turning local goodwill into paid work

Most side hustle advice focuses on selling online, renting out a room or starting a digital business. But there is another option much closer to home: charging fairly for the practical help neighbours already ask for.

Think about the messages that appear in local groups all the time:

  • “Can anyone let the dog out at lunchtime?”
  • “Does anyone know someone who could mow a small lawn?”
  • “Can anyone collect a prescription for my mum?”
  • “Is there someone local who can feed the cat while we’re away?”
  • “Can anyone help my dad set up his new phone?”

These are not fantasy side hustles. They are real, everyday problems. And people often prefer to pay someone local, reliable and already known in the community rather than book a stranger through an app.

This is not about flogging products

Let’s be very clear: this is not about using your local group to sell products, recruit people into schemes or post constant “small business” adverts that turn out to be multi-level marketing.

Most people are tired of that. The beauty products. The wellness powders. The “passive income” pitches. The posts that pretend to be friendly but are really sales funnels.

This article is about something else entirely: offering practical services that solve real local problems.

Do not be this person

  • Do not cold-join a group just to advertise.
  • Do not post every few days.
  • Do not push MLM, pyramid-selling or recruitment-style offers.
  • Do not guilt neighbours into booking you.
  • Do not turn every community conversation into a sales opportunity.

When is it OK to offer your services?

It is usually fine to post about your side hustle if you have genuinely been part of the community first.

Ask yourself:

  • Have I been in the group for a while?
  • Have I helped or contributed before?
  • Would people broadly recognise my name?
  • Am I offering something useful and local?
  • Would this feel like a neighbour sharing a service rather than a stranger dropping an advert?

If the answer is yes, you are probably on safe ground.

Quick rule of thumb

If your first ever contribution to the group is “Hi ladies, I’ve started a new venture!”, it’s probably a no. If you’ve spent two years helping neighbours, answering questions and being part of the community, it’s a very different story.

Five side hustle ideas to offer in your local WhatsApp group

1. Dog walks, pet pop-ins and “let the dog out” visits

This is one of the easiest local services to offer, especially if you are already known as someone who likes animals.

You could offer:

  • letting dogs out for a wee
  • short lunchtime walks
  • cat feeding
  • holiday pet checks
  • feeding fish, rabbits or guinea pigs

What to charge:

  • £8–£12 for a 15-minute pet pop-in
  • £12–£18 for a 30-minute dog walk
  • £20–£30 for two visits in one day
  • £10–£15 for cat feeding or small pet checks

MoneyMagpie Tip

If you are already checking on several neighbours’ dogs most weeks for free, it may no longer be a favour. It may be an unpaid job. Emergency one-offs can stay free if you want, but regular weekly care should be priced.

2. Lawn mowing and garden tidy-ups

Lots of people do not need a professional gardener. They just need someone to mow the lawn, sweep leaves, water pots or tidy the garden before visitors arrive.

What to charge:

  • £15–£25 for a small lawn mow
  • £25–£40 for a larger garden tidy
  • £15 per half hour for weeding, watering or general upkeep
  • a monthly price for regular customers

3. Click-and-collect, prescription runs and errands

This is one of the best post-pandemic side hustle ideas because it started as community help and still solves a real problem.

You could offer:

  • prescription collections
  • click-and-collect pickups
  • parcel drop-offs
  • small emergency shops
  • dry-cleaning collections

What to charge:

  • £5–£8 for a quick local collection
  • £10–£15 for a larger errand run
  • £20+ for multiple errands in one trip
  • a weekly regular slot for repeat clients

Why this works so well

This kind of errand service is one of the easiest local side hustles to start because it doesn’t need specialist qualifications – just reliability, flexibility and a willingness to help with the jobs people struggle to fit into the day.

4. Holiday house checks, plant watering and cat feeding

When people go away, they often need someone to water plants, put bins out, check post, feed cats or make sure the house looks occupied.

What to charge:

  • £8–£12 for a short visit
  • £15–£25 for a longer visit with pet care
  • £40–£70 per week for a simple house-check package

5. Tech help and life admin support

This is the sleeper hit. Every community has people who need help with everyday tech and admin but do not know who to ask.

You could help with:

  • setting up phones or tablets
  • printing return labels
  • online forms
  • scanning documents
  • Zoom, WhatsApp or smart TV setup
  • basic digital troubleshooting

What to charge:

  • £15–£20 for 30 minutes
  • £25–£35 for a one-hour home visit
  • £10 for quick one-off tasks

The side hustle people forget

Tech help is often overlooked because it sounds too small to be a “real” business. But helping someone set up a phone, print labels or navigate online forms is exactly the kind of practical task people ask about in local groups all the time.

How often should you post?

Less often than you think.

The point is not to become a permanent advert in everyone’s pocket. Post once clearly, then let recommendations, repeat customers and word of mouth do the work.

Posting rules

Do:

  • Post one clear introductory message.
  • Post again when it is seasonally relevant.
  • Reply when someone directly asks for recommendations.
  • Ask happy customers if they would recommend you.

Don’t:

  • Bump your advert every week.
  • Hijack unrelated posts.
  • Use pushy sales language.
  • Copy and paste the same message constantly.

As a rule, posting about your service once every couple of months is plenty unless the group has a specific day or thread for local businesses.

What language should you use?

The best posts sound neighbourly, clear and low-pressure.

Use phrases like:

  • “If it’s useful…”
  • “I’m now offering…”
  • “Happy to help with…”
  • “I’ve got room for a couple of local clients.”
  • “Feel free to message me if you’d like details.”

Avoid phrases like:

  • “Exciting opportunity”
  • “DM me hun”
  • “Passive income”
  • “Boss babe”
  • “Limited spaces” unless you really mean it

Example of good wording

“Hi everyone – I’m based in and I’m now offering local pet pop-ins, dog walks and small errand runs. I already help a few neighbours and thought I’d mention it here in case it’s useful to anyone else. Happy to chat through what’s needed.”

What if you have already been doing it for free?

This is the awkward bit, and it happens a lot.

Maybe you started checking on a neighbour’s dog during the pandemic. Then another neighbour asked. Then someone else needed help. Suddenly you are letting out five dogs most weeks, doing the odd walk and fitting your day around everyone else’s pets.

You never charged because it started as kindness. But now it is regular, time-consuming and starting to look like a job.

The answer is not to send a backdated invoice. It is to reset expectations going forward.

Script to move from free favour to paid service

“I’ve really enjoyed helping with the dogs and I’m very happy to keep doing it when I can. Because it has become a regular part of my week, I’m starting to offer pet visits and dog walks more formally as a paid side service. From [date], regular visits will be £X and walks will be £Y. I wanted to give you plenty of notice so you can decide what works best for you.”

An easier way to think about it

You are not suddenly charging for kindness. You are separating one-off neighbourly favours from repeat weekly care. That is a perfectly fair boundary to draw.

A WhatsApp post you can adapt

“Hi everyone – after helping a few neighbours with dog walks, pet pop-ins and errands over the last couple of years, I’m starting to offer it more formally as a small local side hustle. I’m based in and can help with dog walks, letting pets out for a wee, cat feeding, holiday pet checks, simple errand runs and the odd garden job. Prices depend on what’s needed, but I’m very happy to chat it through. If it’s useful, feel free to drop me a message.”

The bottom line

If your local WhatsApp group is full of pyramid sellers and constant product posts, it is easy to assume there is no tasteful way to use it for business.

But there is.

The trick is to stop thinking, “What can I sell these people?” and start thinking, “What do people in this community already need help with, and could I offer that reliably for a fair price?”

Your neighbours probably do not want another sales pitch. They may well want someone trustworthy who can check on the dog, collect a prescription, water the tomatoes, mow the lawn or sort out the printer.

And if you are already the person quietly doing those things for free, your WhatsApp group might not just be where the work comes from.

It might be the place you realise you had a side hustle all along.

Bottom line

The best WhatsApp-group side hustles are not the spammiest ones. They are the useful, trustworthy, local services people genuinely need – offered by someone who already feels like part of the community.

FAQs

Can I advertise my side hustle in a local WhatsApp group?

Yes, if you are already part of the community and are offering a genuinely useful local service. Keep the post clear, friendly and low-pressure.

How often should I post about my services?

Usually once every couple of months is enough, unless the group has a specific local business thread. It is better to rely on recommendations than constant posting.

What are good side hustles for local WhatsApp groups?

Good options include dog walking, pet sitting, lawn mowing, click-and-collect runs, prescription collections, holiday house checks, plant watering and tech help.

Should I charge neighbours if I used to help for free?

Yes, if the favour has become regular. One-off emergency help can stay free, but repeated weekly work should be priced fairly.

How do I avoid sounding like a pyramid seller?

Offer a practical service, not a vague opportunity. Avoid phrases like DM me hun, passive income or exciting business opportunity. Be specific about what you do and what it costs.

{
“@context”: “https://schema.org”,
“@type”: “Article”,
“headline”: “The Side Hustle Hiding in Your Local WhatsApp Group – Without Annoying the Neighbours”,
“description”: “How to use your local WhatsApp or Facebook group to offer genuine side hustle services such as dog walking, errands, gardening and pet care without spammy selling.”,
“author”: {
“@type”: “Organization”,
“name”: “MoneyMagpie”
},
“publisher”: {
“@type”: “Organization”,
“name”: “MoneyMagpie”
},
“mainEntityOfPage”: {
“@type”: “WebPage”,
“@id”: “https://www.moneymagpie.com/”
},
“articleSection”: “Make Money”,
“keywords”: [
“side hustle”,
“local WhatsApp group”,
“make money locally”,
“dog walking side hustle”,
“pet sitting”,
“errand service”,
“make money from home”,
“community side hustle”
]
}

{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “Can I advertise my side hustle in a local WhatsApp group?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Yes, if you are already part of the community and are offering a genuinely useful local service. Keep the post clear, friendly and low-pressure.”
}
},
{
“@type”: “Question”,
“name”: “How often should I post about my services?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Usually once every couple of months is enough, unless the group has a specific local business thread. It is better to rely on recommendations than constant posting.”
}
},
{
“@type”: “Question”,
“name”: “What are good side hustles for local WhatsApp groups?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Good options include dog walking, pet sitting, lawn mowing, click-and-collect runs, prescription collections, holiday house checks, plant watering and tech help.”
}
},
{
“@type”: “Question”,
“name”: “Should I charge neighbours if I used to help for free?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Yes, if the favour has become regular. One-off emergency help can stay free, but repeated weekly work should be priced fairly.”
}
},
{
“@type”: “Question”,
“name”: “How do I avoid sounding like a pyramid seller?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Offer a practical service, not a vague opportunity. Avoid phrases like DM me hun, passive income or exciting business opportunity. Be specific about what you do and what it costs.”
}
}
]
}

“`

The post The Side Hustle Hiding in Your Local WhatsApp Group – Without Annoying the Neighbours appeared first on MoneyMagpie.

Original source: https://www.moneymagpie.com/make-money/the-side-hustle-hiding-in-your-local-whatsapp-group-without-annoying-the-neighbours

The 2026 Homebuying Checklist for Veterans and Military Families

Home Business Magazine Online

Buying a home can raise questions that go beyond price and location.

Will the payment fit the budget? What will the lender need? Does the buyer qualify? Will the home meet the loan requirements?

The homebuying checklist ahead helps veterans and military families sort through those details early, from the monthly budget and paperwork to lender conversations and preapproval.

1. Start With the Monthly Payment

The price on the listing is only part of the story. What matters day-to-day is the payment that comes after the keys are handed over.

Before you see a house, sit down with the monthly cost. Add the mortgage, taxes, insurance, utilities, basic upkeep, any HOA fees, and what it will cost to move.

Use the latest rate quote when estimating the monthly payment. Even a small rate change can affect what you pay each month.

Military families may also need extra room in the budget during a move. A spouse may be between jobs, the commute may be longer, or the family may need to stay close to a school, base, workplace, or medical provider.

If you have self-employment income, side business income, or changing household income, ask the lender early how that income will be reviewed.

2. Check Credit, Income, and Debt

VA-backed loans can help, but the lender still needs to see where you stand financially.

They will look at your income, credit, debt, work history, and whether the payment is something you can realistically afford.

Before applying, check your credit report, look at your card balances, and try not to take on new debt unless you have to. The goal is not perfect finances. It is knowing what a lender may see before you apply.

3. Confirm VA Loan Eligibility

For veterans and military families, a homebuying checklist makes it easier to check eligibility before the home search goes too far.

The Certificate of Eligibility, or COE, shows the lender that the borrower qualifies for the VA home loan benefit. VA.gov says requesting the COE is the first step in getting a VA-backed home loan.

Before looking closely at homes or asking lenders for numbers, buyers should review their VA home loan eligibility so they know what they may qualify for and what paperwork may be needed.

Eligibility is only the beginning. The lender still has to review the borrower’s finances and the property before approving the loan.

4. Gather Documents Early

Paperwork is easier when there is no deadline hanging over it.

Your lender will ask for the basics: ID, income, work history, bank records, and any service paperwork needed for the COE. If you work for yourself, expect a few extra questions about income. Business tax returns, profit and loss details, or extra bank statements may be part of it.

Keep everything in one folder, digital or physical. When the lender asks for an updated record, you will not have to dig for it.

5. Compare Lenders

Talk to a few lenders before choosing one.

A lower rate helps, but it is not the only thing to compare. Look at the fees, closing costs, timeline, and how clearly the lender answers questions.

If you’re going with a VA-backed loan, ask the lender how often they work with them. You’ll want someone who can explain the COE, appraisal, paperwork, and next steps clearly, without making the whole process feel overwhelming.

6. Understand the Home Requirements

Home Requirements
Pexels

The home needs to fit the family’s needs, budget, and long-term plans.

VA-backed loans are generally for primary residences. The property also needs to meet basic standards for safety, soundness, and livability.

An appraisal can help review value and certain property conditions. A home inspection is different. It can help buyers understand repairs or future costs.

An older roof, aging HVAC system, or plumbing issue may not seem urgent during a showing. After closing, those costs can feel very real.

7. Get Preapproved Before Making an Offer

Preapproval helps buyers know what price range they’re working with before they make an offer. It also gives sellers peace of mind that the buyer has already talked to a lender.

For Veterans and military families, preapproval can answer practical questions early: What can we afford? Which documents are missing? How quickly could we move if we find the right home?

Those answers can keep the search focused.

Final Thoughts

Buying a home is about more than the listing. The payment, paperwork, moving costs, and repairs all matter once you are actually living there.

For veterans and military families, following a homebuying checklist can search go more smoothly when a few things are sorted out early: the budget, eligibility, documents, lender options, and home requirements.

The right home matters. Being ready for it matters, too.

The post The 2026 Homebuying Checklist for Veterans and Military Families appeared first on Home Business Magazine.

Original source: https://homebusinessmag.com/blog/financing/2026-homebuying-checklist-veterans-military-families/

How to Make Money Selling Homemade Jam and Chutney

Love making jam, chutney or marmalade? Your kitchen hobby could become a profitable side hustle — but only if you do it properly.

Homemade preserves are brilliant small-business products. They are relatively low-cost to make, easy to batch-produce, attractive as gifts and ideal for selling at markets, online, through social media or via local farm shops and delis.

But because you are selling food, there are legal and safety rules to follow. This guide explains how to start selling homemade jams and chutneys in the UK, including registration, food hygiene, labelling, pricing and where to sell.

At a glance

  • You can sell homemade jam and chutney from home in the UK, but you usually need to register as a food business.
  • You should register with your local authority at least 28 days before trading.
  • Your jars need compliant labels, including ingredients, allergens, best-before date, net weight and business details.
  • Pricing must include jars, labels, energy, market fees, packaging and your time — not just ingredients.
  • Start with one or two products, sell locally first, then scale once you know what works.

Can you make money selling homemade jam and chutney?

Yes. Selling homemade preserves can be a very good side hustle, especially if you enjoy cooking, have access to seasonal fruit or vegetables, and like the idea of building a small food brand.

A jar of homemade jam or chutney might sell for around £3.50 to £6.50, depending on the ingredients, jar size, branding and where it is sold. Premium flavours, local ingredients and gift sets can often command more.

The key is margin. A jar that costs £1.50 to make and sells for £5 gives you room for profit. A jar that costs £3.20 to make and sells for £4.50 leaves very little once you include time, packaging and fees.

Why jams and chutneys work well as a side hustle

Jams, chutneys and preserves are popular because they are familiar, giftable and easy to sell in small batches. You do not need to launch with a huge product range or expensive premises. Many small sellers start from a domestic kitchen, provided it is suitable and they follow food safety rules.

They also suit seasonal selling. Think strawberry jam in summer, blackberry and apple jam in autumn, and spiced chutney gift sets at Christmas.

How to get started in 10 steps

  1. Choose one or two products. Start with a simple range, such as one jam and one chutney.
  2. Cost each recipe. Include fruit, sugar, vinegar, spices, jars, lids, labels, energy, packaging and your time.
  3. Standardise your recipe. Write down exact weights, timings, temperatures and jar yield.
  4. Register your food business. Do this with your local authority at least 28 days before selling.
  5. Prepare your kitchen. Set up cleaning routines, safe storage, pest control and food-safe working areas.
  6. Create food safety paperwork. Keep batch sheets, supplier records, cleaning logs and allergen notes.
  7. Take food hygiene training. A Level 2 Food Hygiene/Food Safety course is a sensible starting point.
  8. Design compliant labels. Include the food name, ingredients, allergens, best-before date, net weight and business details.
  9. Pick your first sales channel. Try markets, local shops, social media, Etsy or your own website.
  10. Launch small and improve. Sell a test batch, collect feedback, adjust pricing and scale your bestsellers.

The legal basics of selling jam and chutney in the UK

1. Register as a food business

If you prepare, store, handle or sell food, you will usually need to register your food business with your local authority. This applies whether you sell from home, online, at markets, through social media or to local shops.

Registration is generally free and should be done at least 28 days before you start trading.

2. Make sure your home kitchen is suitable

You do not necessarily need a commercial kitchen to start. However, your domestic kitchen must be clean, organised and suitable for producing food safely.

You should think about washable surfaces, handwashing, ingredient storage, keeping pets away during production, pest control, cleaning routines and safe storage for finished jars.

3. Follow food safety rules

When you sell food, you are responsible for making sure it is safe to eat. For jam and chutney, this includes using safe recipes, clean jars and lids, proper sterilising methods, reliable batch records and suitable storage instructions.

Be especially careful with low-sugar recipes, unusual ingredients or anything where the acidity, sugar level or shelf life may not be straightforward.

4. Keep basic food safety records

A small food business should have a food safety management system based on HACCP principles. In plain English, this means you should know what could go wrong and how you prevent it.

Keep records of:

  • ingredients and suppliers
  • batch dates
  • recipe quantities
  • jar numbers or batch codes
  • cleaning routines
  • allergens
  • where batches were sold

5. Label your jars correctly

Pre-packed jars usually need a clear label including:

  • name of the food
  • ingredients list in descending weight order
  • allergen information clearly emphasised
  • best-before date
  • net weight
  • storage instructions where needed
  • business name and address
  • batch or lot information

If you describe a product as jam, jelly or marmalade, be aware that those names have specific compositional and labelling rules. For example, jam labels may need fruit and sugar content statements.

Important legal note

Food rules can vary depending on what you sell, how you package it and where in the UK you are based. Always check with your local authority or environmental health team before launching.

What equipment do you need?

You can start small, but you will need reliable, clean equipment. Useful basics include:

  • large preserving pan or heavy stock pot
  • digital scales
  • jam funnel
  • ladle
  • sugar thermometer or digital probe thermometer
  • glass jars and new lids
  • labels
  • cleaning products suitable for food preparation areas
  • storage boxes or shelving
  • batch record spreadsheet or notebook

Best jam and chutney ideas to sell

Do not launch with too many flavours. A small, strong range is easier to make, label, price and sell.

Good beginner jam ideas

  • strawberry jam
  • raspberry jam
  • blackberry and apple jam
  • rhubarb and ginger jam
  • chilli jam

Good beginner chutney ideas

  • caramelised onion chutney
  • tomato chutney
  • apple chutney
  • mango chutney
  • spiced Christmas chutney

How to price homemade jam and chutney

Many new sellers undercharge because they only count ingredients. You must include every cost.

Your price should cover:

  • ingredients
  • jars and lids
  • labels
  • tamper seals or tags
  • energy
  • cleaning products
  • market stall fees
  • card payment fees
  • website or marketplace fees
  • postage and packaging
  • your time

Simple pricing example

Imagine one batch makes 12 jars of chutney.

  • Ingredients: £11
  • Jars and lids: £8.40
  • Labels and seals: £3.60
  • Energy and cleaning: £2
  • Market/overhead allowance: £3

Total batch cost: £28

Cost per jar: £2.33

If you sell each jar for £4.95, turnover is £59.40 and gross margin before wider business costs is £31.40.

Where to sell homemade jam and chutney

Farmers’ markets and craft fairs

Markets are one of the easiest places to start. You get instant feedback, can offer samples where permitted, and can sell gift sets face to face.

Local shops and delis

Farm shops, independent delis, butchers, bakeries and gift shops may be open to stocking local preserves. Take samples, a price list and clear product information.

Social media

Instagram, Facebook and local community groups can work well for seasonal launches, limited batches and local delivery.

Etsy and online marketplaces

Marketplaces can work for gift sets, but fees and postage costs must be built into your pricing.

Your own website

A website is best for long-term brand building. It gives you control over your product pages, email list, SEO and repeat customers.

How to make your products stand out

Good branding makes a homemade product feel professional and giftable. Focus on clear labels, consistent jars, attractive photography and flavour names that people understand.

For example, “Spiced Plum Christmas Chutney” is clearer than “Winter Warmer”. You can still add personality in the description.

Do you need insurance?

Product liability and public liability insurance are strongly recommended when selling food. Some markets and retailers may require proof of insurance before allowing you to trade.

Do you need to tell HMRC?

If you are selling regularly and making money, keep proper records of income and expenses. Depending on your earnings and circumstances, you may need to register as self-employed and declare your income to HMRC.

Common mistakes to avoid

  • pricing too cheaply
  • launching too many flavours
  • guessing shelf life
  • forgetting allergen labelling
  • not registering as a food business
  • using inconsistent recipes
  • failing to keep batch records
  • ignoring postage and packaging costs

Is selling jam and chutney worth it?

Yes — if you enjoy making preserves and are prepared to treat it like a real food business.

Start with a small range, register properly, label your jars correctly and price for profit. Then test your products at local markets, through social media or with independent shops.

It may begin with a few jars on a kitchen table, but with the right systems and branding, homemade jam and chutney can become a reliable long-term side hustle.

FAQs

Can I sell homemade jam from home in the UK?

Yes, but you will usually need to register as a food business with your local authority and make sure your kitchen and processes are suitable for producing food safely.

Do I need a food hygiene certificate to sell jam?

You need to understand food hygiene and handle food safely. A Level 2 Food Hygiene/Food Safety course is a sensible and inexpensive way to show you have basic training.

Do I need to register with the council to sell chutney?

Usually yes. If you are preparing or selling food, you should register with your local authority at least 28 days before trading.

What needs to go on a homemade jam label?

Your label will usually need the food name, ingredients list, allergens, best-before date, net weight, storage instructions where needed, business name and address, and batch information.

Can I sell jam on Facebook or Etsy?

Yes, but online selling still counts as selling food. You must follow food business registration, food safety and labelling rules.

How much should I charge for homemade jam?

Many small sellers charge around £3.50 to £6.50 per jar, depending on ingredients, size, packaging and sales channel. Always calculate your real cost per jar before setting your price.

Read about how to set up a cake shed here. 

{
“@context”: “https://schema.org”,
“@graph”: [
{
“@type”: “Article”,
“@id”: “https://www.moneymagpie.com/make-money/how-to-make-money-selling-homemade-jam-and-chutney#article”,
“headline”: “How to Make Money Selling Homemade Jam and Chutney”,
“description”: “A UK side hustle guide to making money selling homemade jams and chutneys, including legal requirements, food safety, pricing, labelling and where to sell.”,
“author”: {
“@type”: “Organization”,
“name”: “MoneyMagpie”
},
“publisher”: {
“@type”: “Organization”,
“name”: “MoneyMagpie”,
“url”: “https://www.moneymagpie.com”
},
“mainEntityOfPage”: {
“@type”: “WebPage”,
“@id”: “https://www.moneymagpie.com/make-money/how-to-make-money-selling-homemade-jam-and-chutney”
}
},
{
“@type”: “HowTo”,
“@id”: “https://www.moneymagpie.com/make-money/how-to-make-money-selling-homemade-jam-and-chutney#howto”,
“name”: “How to start selling homemade jam and chutney”,
“description”: “A step-by-step guide to starting a homemade jam or chutney side hustle in the UK.”,
“step”: [
{
“@type”: “HowToStep”,
“name”: “Choose one or two products”,
“text”: “Start with a simple range, such as one jam and one chutney.”
},
{
“@type”: “HowToStep”,
“name”: “Cost each recipe”,
“text”: “Include ingredients, jars, lids, labels, energy, packaging and your time.”
},
{
“@type”: “HowToStep”,
“name”: “Standardise your recipe”,
“text”: “Write down exact weights, timings, temperatures and jar yield.”
},
{
“@type”: “HowToStep”,
“name”: “Register your food business”,
“text”: “Register with your local authority at least 28 days before selling.”
},
{
“@type”: “HowToStep”,
“name”: “Prepare your kitchen”,
“text”: “Set up cleaning routines, safe storage and food-safe working areas.”
},
{
“@type”: “HowToStep”,
“name”: “Create food safety paperwork”,
“text”: “Keep batch sheets, supplier records, cleaning logs and allergen notes.”
},
{
“@type”: “HowToStep”,
“name”: “Take food hygiene training”,
“text”: “A Level 2 Food Hygiene or Food Safety course is a sensible starting point.”
},
{
“@type”: “HowToStep”,
“name”: “Design compliant labels”,
“text”: “Include the food name, ingredients, allergens, best-before date, net weight and business details.”
},
{
“@type”: “HowToStep”,
“name”: “Pick your first sales channel”,
“text”: “Try markets, local shops, social media, Etsy or your own website.”
},
{
“@type”: “HowToStep”,
“name”: “Launch small and improve”,
“text”: “Sell a test batch, collect feedback, adjust pricing and scale your bestsellers.”
}
]
},
{
“@type”: “FAQPage”,
“@id”: “https://www.moneymagpie.com/make-money/how-to-make-money-selling-homemade-jam-and-chutney#faq”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “Can I sell homemade jam from home in the UK?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Yes, but you will usually need to register as a food business with your local authority and make sure your kitchen and processes are suitable for producing food safely.”
}
},
{
“@type”: “Question”,
“name”: “Do I need a food hygiene certificate to sell jam?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “You need to understand food hygiene and handle food safely. A Level 2 Food Hygiene or Food Safety course is a sensible way to show basic training.”
}
},
{
“@type”: “Question”,
“name”: “Do I need to register with the council to sell chutney?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Usually yes. If you are preparing or selling food, you should register with your local authority at least 28 days before trading.”
}
},
{
“@type”: “Question”,
“name”: “What needs to go on a homemade jam label?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “A homemade jam label will usually need the food name, ingredients list, allergens, best-before date, net weight, storage instructions where needed, business name and address, and batch information.”
}
},
{
“@type”: “Question”,
“name”: “Can I sell jam on Facebook or Etsy?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Yes, but online selling still counts as selling food. You must follow food business registration, food safety and labelling rules.”
}
},
{
“@type”: “Question”,
“name”: “How much should I charge for homemade jam?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Many small sellers charge around £3.50 to £6.50 per jar, depending on ingredients, size, packaging and sales channel. Always calculate your real cost per jar before setting your price.”
}
}
]
}
]
}

“`

The post How to Make Money Selling Homemade Jam and Chutney appeared first on MoneyMagpie.

Original source: https://www.moneymagpie.com/make-money/how-to-make-money-selling-homemade-jam-and-chutney

HVAC Industry Trends for the Future

Home Business Magazine Online

The HVAC industry is constantly evolving due to new technologies, shifts in consumer preferences, and a focus on greater eco-friendliness. If you’re a homeowner considering an upgrade or a business leader looking to invest, understanding these HVAC industry trends can help you make better choices.

With rising energy costs and environmental concerns, many manufacturers are developing systems to reduce energy use and tap renewable energy sources. Smart thermostats and advanced HVAC systems with AI and IoT features help users optimize energy consumption. These are just some of the emerging industry practices for the future.

Here are some key trends in the HVAC industry.

Smart Technology Integration

One major trend in HVAC is the use of smart technology. Smart thermostats and connected systems let you control your heating and cooling from your phone. You can change the temperature in your home even when you’re away. These systems learn your routines and help save energy while keeping you comfortable.

Also, connecting your HVAC system with other smart home devices makes it even better. For example, your system can adjust based on the weather or your daily schedule. This automation improves comfort and reduces energy consumption, benefiting both users and the planet.

AC Installation Innovations

When it comes to air conditioner installation, the landscape is shifting. The traditional split system is being complemented, and in some cases replaced, by newer configurations such as ductless mini-splits or packaged systems that offer greater flexibility and efficiency. These systems can be advantageous in homes without existing ductwork, offering an easier, less invasive installation.

On top of that, advancements in installation techniques are making the process quicker and more efficient. With improved training and technology, contractors can complete projects more quickly while maintaining high standards. This means a smoother experience for homeowners, which is always a plus.

Sustainability Takes Center Stage

Given the importance of climate change, the HVAC industry is increasingly focusing on sustainability. New systems use eco-friendly refrigerants that are better for the environment than older ones. There are also more energy-efficient options available, helping you reduce your carbon footprint.

Sustainability isn’t just about the systems. It also includes using responsibly sourced materials and reducing waste during installation. Choosing these options can be a smart decision for both homeowners and businesses, leading to long-term savings on energy costs.

Air Quality Awareness

Indoor air quality has become a growing concern, and the HVAC industry is responding. New filtration systems can capture smaller particles and allergens, including HEPA filters, UV light technology, and ionization systems.

Homeowners are increasingly looking for ways to improve indoor air quality, driving innovation in HVAC technology. This trend helps meet the growing demand for healthier living spaces, thereby improving overall well-being.

AC Repair Changes

As HVAC systems improve, so does AC repair. Technicians now use smart tools to quickly find problems. This makes it easier and faster to repair AC units, saving homeowners time and reducing frustration.

Additionally, technician training now emphasizes modern technologies and eco-friendly practices. This helps repair professionals better understand today’s HVAC systems. When repairs are needed, they can complete them effectively while maintaining quality and safety.

Decentralized Heating and Cooling Systems

A new trend in the HVAC industry is decentralized heating and cooling systems. Instead of using a single central unit to control the temperature of an entire building, these systems allow climate control in different areas. Each room or zone can have its own heating and cooling unit, improving comfort and saving energy.

Decentralized systems are perfect for large homes or commercial spaces where different areas have different heating and cooling needs. By providing just the right climate control for each space, homeowners and business leaders can reduce energy use and costs. These systems can also be powered by renewable energy sources, making them more sustainable.

User Interfaces and Accessibility

HVAC technology is also improving user interfaces. Modern HVAC systems have easy-to-use features that help homeowners adjust settings and monitor performance. Touchscreen panels, mobile apps, and voice-activated controls are now common, allowing users to make quick adjustments.

Accessibility is a key focus for manufacturers. They are creating user interfaces that everyone, including those with disabilities, can use easily. By designing intuitive, accessible systems, HVAC companies ensure that all users can enjoy efficient heating and cooling. This trend is making HVAC systems more user-friendly for everyone.

Energy Efficiency Standards

Governments and organizations are pushing for higher energy efficiency in HVAC systems, leading manufacturers to create products that meet these new standards. This is good for consumers, as they can expect more efficient systems that lower their utility bills.

Energy efficiency is important not just for saving money. It also shows a commitment to protecting the environment. HVAC companies that focus on efficiency will likely improve and stand out in the market as these standards become stricter.

The HVAC industry is changing with a focus on technology, sustainability, and efficiency. As smart technology becomes common and air quality awareness grows, we are moving toward healthier living environments.

The post HVAC Industry Trends for the Future appeared first on Home Business Magazine.

Original source: https://homebusinessmag.com/blog/construction-business/hvac-industry-trends-future/

U.S. Leads the World in Foreign Investment, Creating Opportunities for Small and Home-Based Businesses

Home Business Magazine Online

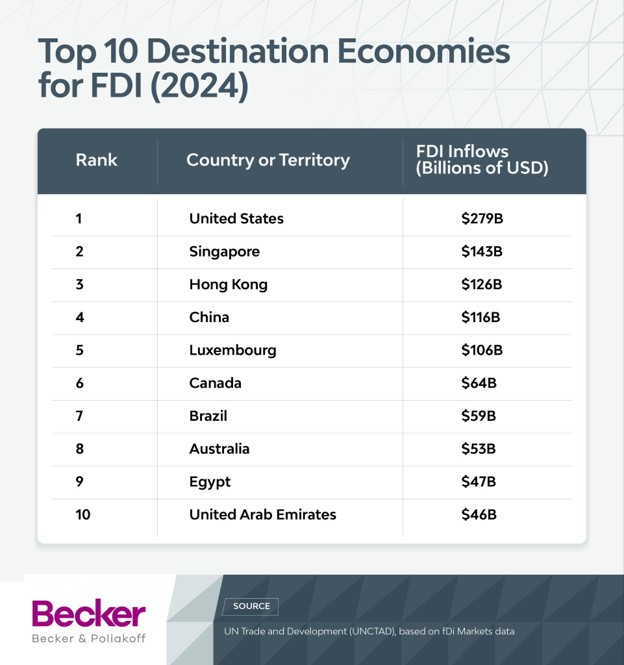
The United States remains the world’s top destination for foreign direct investment, attracting $279 billion in inbound investment in 2024 — more than double the $116 billion attracted by China — according to an analysis of federal data from Becker & Poliakoff.

The report, which analyzed the latest federal foreign investment data, underscores America’s continued dominance in attracting overseas capital at a time when global competition for investment is intensifying. While foreign direct investment, or FDI, is often associated with multinational corporations and large-scale manufacturing projects, the economic activity generated by those investments can create opportunities that ripple throughout local business communities, including home-based businesses.

Foreign Investment Creates Opportunities Beyond Major Corporations

FDI occurs when a company or investor from one country establishes or acquires business operations in another. These investments can include manufacturing plants, distribution centers, research facilities and technology hubs that generate jobs, stimulate local spending and create demand for services from businesses of all sizes.

For entrepreneurs operating from home, major foreign investment projects can translate into new opportunities for consulting, marketing, bookkeeping, recruiting, design, logistics support and other professional services. As foreign-owned companies establish a presence in local markets, they often rely on networks of small vendors and contractors to support their operations.

Top 10 Destination Economies for FDI
https://beckerlawyers.com/

The study found that Texas attracted the most foreign direct investment of any state in 2024, bringing in $22.8 billion. The state’s position was bolstered by Samsung’s ongoing semiconductor manufacturing expansion, which totals approximately $45 billion in planned investment.

Georgia ranked second with $16.3 billion despite being only the nation’s eighth-most-populous state. The state’s strong showing was driven largely by electric vehicle manufacturing investments from Hyundai and Kia, highlighting how targeted industry growth can attract significant international capital.

California ranked third with $12.9 billion in foreign direct investment, followed by Ohio at $7.6 billion. North Carolina and Massachusetts each attracted $5.6 billion, while Florida, New York, Virginia and Washington rounded out the top 10 states.

Manufacturing Leads Investment Growth Across Key States

The concentration of investment in manufacturing was particularly notable. According to the study, manufacturing accounted for a cumulative foreign direct investment position of $2.4 trillion in 2024, more than double the next-largest industry category. The finding reflects continued global demand for U.S.-based production facilities, particularly in sectors such as semiconductors, electric vehicles and advanced technology.

The employment impact is substantial. Foreign-owned companies support roughly 15 million jobs across the United States, according to the analysis. In South Carolina, the influence is especially pronounced, with 8% of all jobs tied to majority foreign-owned companies — the highest share of any state.

The study also found that Japan remains the largest foreign investor in the United States. Japan’s cumulative investment position grew from $694 billion in 2020 to $819 billion in 2024, narrowly surpassing Canada, which held an investment position of $812 billion.

Beyond the headline figures, the data points to the continued strength of the U.S. business environment. Foreign companies often choose investment destinations based on factors such as workforce quality, infrastructure, legal protections and access to customers. Those same advantages can benefit entrepreneurs and home-based business owners looking to build relationships with growing companies entering their markets.

As large foreign-backed projects continue to expand across the country, local entrepreneurs may find new opportunities emerging alongside them. While billion-dollar investments make headlines, the economic activity they generate frequently extends far beyond factory floors and corporate offices, creating demand for the products and services provided by small businesses and independent professionals.

Business owners interested in learning more about the findings can visit https://beckerlawyers.com

The post U.S. Leads the World in Foreign Investment, Creating Opportunities for Small and Home-Based Businesses appeared first on Home Business Magazine.

Original source: https://homebusinessmag.com/newsstand/news/u-s-leads-world-foreign-investment-creating-opportunities-small-home-based-businesses/