Google Analytics 4 introduces benchmarking data

Why the shift from ‘conversions’ to ‘key events’ in GA4 is a game-changer

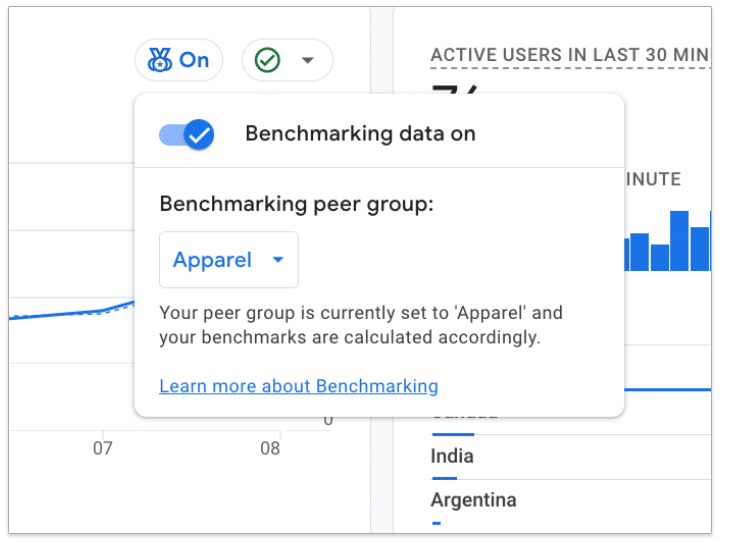
Google rolled out a significant update to Google Analytics 4 (GA4), allowing users to compare their performance with other businesses in their industry.

Why we care: This new feature will provide valuable context for advertisers trying to understand their performance relative to their peers, potentially informing strategic decisions and goal-setting.

How it works.

  • Users can access benchmarking data if their property has the “Modeling contributions & business insights” setting enabled in Admin > Account Settings.
  • Benchmarks are refreshed every 24 hours.
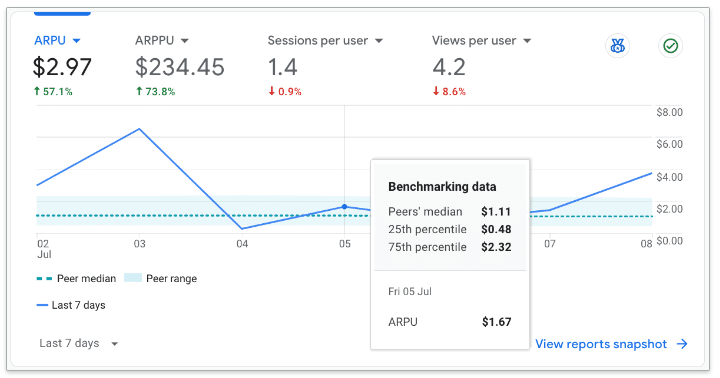
  • The summary displays:
    1. Your trendline.
    2. Median in your peer group.
    3. Range in your peer group (25th to 75th percentile).

Key features.

  • Customizable peer groups: Users can select from various categories to find the most relevant comparison group.
  • Data privacy: Google assures that benchmarking data is encrypted, protected and aggregated to maintain privacy.
  • Wide range of metrics: Covers acquisition, engagement, retention and monetization.

The big picture. This update addresses a long-standing need in the analytics community for comparative data, allowing businesses to gauge their performance more accurately within their industry context.

What’s next. Users are encouraged to check their GA4 accounts for this new feature and explore how it can enhance their analytics insights.

Original source: https://searchengineland.com/google-analytics-4-benchmarking-data-446142

How to deal with debt with a long-term illness

Are you facing debt with a long-term illness and wondering how you’ll manage your money? Ongoing health issues often mean you end up dealing with unpredictable expenses like travelling to appointments, hospital parking, and prescription charges.

It can be challenging both mentally and physically, and can lead to more stress when you’re already feeling the pressure. These financial extras, as well as time off work and a reduced income, can make falling into debt more likely.

If you’re dealing with a long-term illness and are worried about debt, read our advice on what you can do to deal with your financial situation.


Look at how you can manage your finances

Worried couple working out finances

Create a simple budget to make sure your essential living expenses and care costs are taken into account. You can use our free budget template to get started.

Your budget will help you manage your incomings against your outgoings, so you can concentrate on your health instead of worrying about money. It’s also a good way to discover where you could benefit from saving cash.


Check your Statutory Sick Pay entitlement

Woman receiving a bad diagnosis from the doctor

Some people don’t know that you can get Statutory Sick Pay (SSP) for up to 28 weeks if:

  • You’re in work, but can’t attend because you’re ill
  • You were earning an average of at least £123 per week or more in the two months before you couldn’t work

That means you’ll still get paid a specified amount while you’re off work, paid into your bank account the same way you would usually get your wages.

The current entitlement is £116.75 per week for up to 28 weeks. If you’re struggling to keep up with bills or repayments while off work, this kind of entitlement could ease some of the pressure.

Some employers have their own sick pay schemes, so double check with your HR department what you’re entitled to. If you don’t have an HR department, ask your manager, or check your contract.


Use smart ways to reduce your spending

Unhappy disabled woman

Even if you’re already on a tight budget, there are loads of ways you can cut back and save smartly. Use an Ofgem approved switching service to find better deals on your utility bills, look out for free evening and weekend call offers from your phone provider, and find out how to save money on your TV packages.

When it comes to your food shop, you could switch to own brand products or start shopping at a better value supermarket. Cheaper food doesn’t mean losing out on taste!


Claim an income tax refund

Patient in hospital bed

If you’ve had to stop working due to long-term illness, or have reduced hours because of it, you might be able to get a refund of some of the income tax you’ve paid.

It’s worth contacting HMRC to check if you’re entitled to some money back.


Consider ways to increase your income

Calculator

We’re not talking about getting another job or going back to work when you’re not ready, because your health must come first. If you’re off work long-term because of your illness, or have a low income as a result, there may be some benefits you’re entitled to.

Use the StepChange benefits calculator to check what you could be missing, and look into any pensions, savings or investments you might have. This’ll help to make sure you’ve got as much money coming in as possible.


Try reducing your rent or mortgage payments

Unhappy man such in hospital

If you’re on a low income and renting, you can apply for a council tax discount. If you’ve got a mortgage, contact your lender or insurance provider to see if you have insurance in place that covers your payments while you’re ill.

You might have mortgage payment protection, critical illness cover, or income protection insurance to help you cover payments. However, bear in mind that any insurance pay-out could affect state benefit claims you make.


Get free advice to deal with debt

If you’re struggling to pay your bills, use the Stepchange online Debt Remedy tool here for advice and practical solutions to deal with your debt, or give their advisors a call.

They will talk through your finances and give you free and impartial debt advice, as well as recommend a debt solution tailored to your situation.

Also, sign up to our free debt help emails here. They will support you as you work to pay off your debts and get better.


six_magpie

Sign Up – Newsletter

The post How to deal with debt with a long-term illness appeared first on MoneyMagpie.

Original source: https://www.moneymagpie.com/make-money/how-to-deal-with-debt-with-a-long-term-illness

How to deal with debt with a long-term illness

Are you facing debt with a long-term illness and wondering how you’ll manage your money? Ongoing health issues often mean you end up dealing with unpredictable expenses like travelling to appointments, hospital parking, and prescription charges.

It can be challenging both mentally and physically, and can lead to more stress when you’re already feeling the pressure. These financial extras, as well as time off work and a reduced income, can make falling into debt more likely.

If you’re dealing with a long-term illness and are worried about debt, read our advice on what you can do to deal with your financial situation.


Look at how you can manage your finances

Worried couple working out finances

Create a simple budget to make sure your essential living expenses and care costs are taken into account. You can use our free budget template to get started.

Your budget will help you manage your incomings against your outgoings, so you can concentrate on your health instead of worrying about money. It’s also a good way to discover where you could benefit from saving cash.


Check your Statutory Sick Pay entitlement

Woman receiving a bad diagnosis from the doctor

Some people don’t know that you can get Statutory Sick Pay (SSP) for up to 28 weeks if:

  • You’re in work, but can’t attend because you’re ill
  • You were earning an average of at least £123 per week or more in the two months before you couldn’t work

That means you’ll still get paid a specified amount while you’re off work, paid into your bank account the same way you would usually get your wages.

The current entitlement is £116.75 per week for up to 28 weeks. If you’re struggling to keep up with bills or repayments while off work, this kind of entitlement could ease some of the pressure.

Some employers have their own sick pay schemes, so double check with your HR department what you’re entitled to. If you don’t have an HR department, ask your manager, or check your contract.


Use smart ways to reduce your spending

Unhappy disabled woman

Even if you’re already on a tight budget, there are loads of ways you can cut back and save smartly. Use an Ofgem approved switching service to find better deals on your utility bills, look out for free evening and weekend call offers from your phone provider, and find out how to save money on your TV packages.

When it comes to your food shop, you could switch to own brand products or start shopping at a better value supermarket. Cheaper food doesn’t mean losing out on taste!


Claim an income tax refund

Patient in hospital bed

If you’ve had to stop working due to long-term illness, or have reduced hours because of it, you might be able to get a refund of some of the income tax you’ve paid.

It’s worth contacting HMRC to check if you’re entitled to some money back.


Consider ways to increase your income

Calculator

We’re not talking about getting another job or going back to work when you’re not ready, because your health must come first. If you’re off work long-term because of your illness, or have a low income as a result, there may be some benefits you’re entitled to.

Use the StepChange benefits calculator to check what you could be missing, and look into any pensions, savings or investments you might have. This’ll help to make sure you’ve got as much money coming in as possible.


Try reducing your rent or mortgage payments

Unhappy man such in hospital

If you’re on a low income and renting, you can apply for a council tax discount. If you’ve got a mortgage, contact your lender or insurance provider to see if you have insurance in place that covers your payments while you’re ill.

You might have mortgage payment protection, critical illness cover, or income protection insurance to help you cover payments. However, bear in mind that any insurance pay-out could affect state benefit claims you make.


Get free advice to deal with debt

If you’re struggling to pay your bills, use the Stepchange online Debt Remedy tool here for advice and practical solutions to deal with your debt, or give their advisors a call.

They will talk through your finances and give you free and impartial debt advice, as well as recommend a debt solution tailored to your situation.

Also, sign up to our free debt help emails here. They will support you as you work to pay off your debts and get better.


six_magpie

Sign Up – Newsletter

The post How to deal with debt with a long-term illness appeared first on MoneyMagpie.

Original source: https://www.moneymagpie.com/make-money/how-to-deal-with-debt-with-a-long-term-illness

How to deal with debt with a long-term illness

Are you facing debt with a long-term illness and wondering how you’ll manage your money? Ongoing health issues often mean you end up dealing with unpredictable expenses like travelling to appointments, hospital parking, and prescription charges.

It can be challenging both mentally and physically, and can lead to more stress when you’re already feeling the pressure. These financial extras, as well as time off work and a reduced income, can make falling into debt more likely.

If you’re dealing with a long-term illness and are worried about debt, read our advice on what you can do to deal with your financial situation.


Look at how you can manage your finances

Worried couple working out finances

Create a simple budget to make sure your essential living expenses and care costs are taken into account. You can use our free budget template to get started.

Your budget will help you manage your incomings against your outgoings, so you can concentrate on your health instead of worrying about money. It’s also a good way to discover where you could benefit from saving cash.


Check your Statutory Sick Pay entitlement

Woman receiving a bad diagnosis from the doctor

Some people don’t know that you can get Statutory Sick Pay (SSP) for up to 28 weeks if:

  • You’re in work, but can’t attend because you’re ill
  • You were earning an average of at least £123 per week or more in the two months before you couldn’t work

That means you’ll still get paid a specified amount while you’re off work, paid into your bank account the same way you would usually get your wages.

The current entitlement is £116.75 per week for up to 28 weeks. If you’re struggling to keep up with bills or repayments while off work, this kind of entitlement could ease some of the pressure.

Some employers have their own sick pay schemes, so double check with your HR department what you’re entitled to. If you don’t have an HR department, ask your manager, or check your contract.


Use smart ways to reduce your spending

Unhappy disabled woman

Even if you’re already on a tight budget, there are loads of ways you can cut back and save smartly. Use an Ofgem approved switching service to find better deals on your utility bills, look out for free evening and weekend call offers from your phone provider, and find out how to save money on your TV packages.

When it comes to your food shop, you could switch to own brand products or start shopping at a better value supermarket. Cheaper food doesn’t mean losing out on taste!


Claim an income tax refund

Patient in hospital bed

If you’ve had to stop working due to long-term illness, or have reduced hours because of it, you might be able to get a refund of some of the income tax you’ve paid.

It’s worth contacting HMRC to check if you’re entitled to some money back.


Consider ways to increase your income

Calculator

We’re not talking about getting another job or going back to work when you’re not ready, because your health must come first. If you’re off work long-term because of your illness, or have a low income as a result, there may be some benefits you’re entitled to.

Use the StepChange benefits calculator to check what you could be missing, and look into any pensions, savings or investments you might have. This’ll help to make sure you’ve got as much money coming in as possible.


Try reducing your rent or mortgage payments

Unhappy man such in hospital

If you’re on a low income and renting, you can apply for a council tax discount. If you’ve got a mortgage, contact your lender or insurance provider to see if you have insurance in place that covers your payments while you’re ill.

You might have mortgage payment protection, critical illness cover, or income protection insurance to help you cover payments. However, bear in mind that any insurance pay-out could affect state benefit claims you make.


Get free advice to deal with debt

If you’re struggling to pay your bills, use the Stepchange online Debt Remedy tool here for advice and practical solutions to deal with your debt, or give their advisors a call.

They will talk through your finances and give you free and impartial debt advice, as well as recommend a debt solution tailored to your situation.

Also, sign up to our free debt help emails here. They will support you as you work to pay off your debts and get better.


six_magpie

Sign Up – Newsletter

The post How to deal with debt with a long-term illness appeared first on MoneyMagpie.

Original source: https://www.moneymagpie.com/make-money/how-to-deal-with-debt-with-a-long-term-illness

How to deal with debt with a long-term illness

Are you facing debt with a long-term illness and wondering how you’ll manage your money? Ongoing health issues often mean you end up dealing with unpredictable expenses like travelling to appointments, hospital parking, and prescription charges.

It can be challenging both mentally and physically, and can lead to more stress when you’re already feeling the pressure. These financial extras, as well as time off work and a reduced income, can make falling into debt more likely.

If you’re dealing with a long-term illness and are worried about debt, read our advice on what you can do to deal with your financial situation.


Look at how you can manage your finances

Worried couple working out finances

Create a simple budget to make sure your essential living expenses and care costs are taken into account. You can use our free budget template to get started.

Your budget will help you manage your incomings against your outgoings, so you can concentrate on your health instead of worrying about money. It’s also a good way to discover where you could benefit from saving cash.


Check your Statutory Sick Pay entitlement

Woman receiving a bad diagnosis from the doctor

Some people don’t know that you can get Statutory Sick Pay (SSP) for up to 28 weeks if:

  • You’re in work, but can’t attend because you’re ill
  • You were earning an average of at least £123 per week or more in the two months before you couldn’t work

That means you’ll still get paid a specified amount while you’re off work, paid into your bank account the same way you would usually get your wages.

The current entitlement is £116.75 per week for up to 28 weeks. If you’re struggling to keep up with bills or repayments while off work, this kind of entitlement could ease some of the pressure.

Some employers have their own sick pay schemes, so double check with your HR department what you’re entitled to. If you don’t have an HR department, ask your manager, or check your contract.


Use smart ways to reduce your spending

Unhappy disabled woman

Even if you’re already on a tight budget, there are loads of ways you can cut back and save smartly. Use an Ofgem approved switching service to find better deals on your utility bills, look out for free evening and weekend call offers from your phone provider, and find out how to save money on your TV packages.

When it comes to your food shop, you could switch to own brand products or start shopping at a better value supermarket. Cheaper food doesn’t mean losing out on taste!


Claim an income tax refund

Patient in hospital bed

If you’ve had to stop working due to long-term illness, or have reduced hours because of it, you might be able to get a refund of some of the income tax you’ve paid.

It’s worth contacting HMRC to check if you’re entitled to some money back.


Consider ways to increase your income

Calculator

We’re not talking about getting another job or going back to work when you’re not ready, because your health must come first. If you’re off work long-term because of your illness, or have a low income as a result, there may be some benefits you’re entitled to.

Use the StepChange benefits calculator to check what you could be missing, and look into any pensions, savings or investments you might have. This’ll help to make sure you’ve got as much money coming in as possible.


Try reducing your rent or mortgage payments

Unhappy man such in hospital

If you’re on a low income and renting, you can apply for a council tax discount. If you’ve got a mortgage, contact your lender or insurance provider to see if you have insurance in place that covers your payments while you’re ill.

You might have mortgage payment protection, critical illness cover, or income protection insurance to help you cover payments. However, bear in mind that any insurance pay-out could affect state benefit claims you make.


Get free advice to deal with debt

If you’re struggling to pay your bills, use the Stepchange online Debt Remedy tool here for advice and practical solutions to deal with your debt, or give their advisors a call.

They will talk through your finances and give you free and impartial debt advice, as well as recommend a debt solution tailored to your situation.

Also, sign up to our free debt help emails here. They will support you as you work to pay off your debts and get better.


six_magpie

Sign Up – Newsletter

The post How to deal with debt with a long-term illness appeared first on MoneyMagpie.

Original source: https://www.moneymagpie.com/make-money/how-to-deal-with-debt-with-a-long-term-illness

How to deal with debt with a long-term illness

Are you facing debt with a long-term illness and wondering how you’ll manage your money? Ongoing health issues often mean you end up dealing with unpredictable expenses like travelling to appointments, hospital parking, and prescription charges.

It can be challenging both mentally and physically, and can lead to more stress when you’re already feeling the pressure. These financial extras, as well as time off work and a reduced income, can make falling into debt more likely.

If you’re dealing with a long-term illness and are worried about debt, read our advice on what you can do to deal with your financial situation.


Look at how you can manage your finances

Worried couple working out finances

Create a simple budget to make sure your essential living expenses and care costs are taken into account. You can use our free budget template to get started.

Your budget will help you manage your incomings against your outgoings, so you can concentrate on your health instead of worrying about money. It’s also a good way to discover where you could benefit from saving cash.


Check your Statutory Sick Pay entitlement

Woman receiving a bad diagnosis from the doctor

Some people don’t know that you can get Statutory Sick Pay (SSP) for up to 28 weeks if:

  • You’re in work, but can’t attend because you’re ill
  • You were earning an average of at least £123 per week or more in the two months before you couldn’t work

That means you’ll still get paid a specified amount while you’re off work, paid into your bank account the same way you would usually get your wages.

The current entitlement is £116.75 per week for up to 28 weeks. If you’re struggling to keep up with bills or repayments while off work, this kind of entitlement could ease some of the pressure.

Some employers have their own sick pay schemes, so double check with your HR department what you’re entitled to. If you don’t have an HR department, ask your manager, or check your contract.


Use smart ways to reduce your spending

Unhappy disabled woman

Even if you’re already on a tight budget, there are loads of ways you can cut back and save smartly. Use an Ofgem approved switching service to find better deals on your utility bills, look out for free evening and weekend call offers from your phone provider, and find out how to save money on your TV packages.

When it comes to your food shop, you could switch to own brand products or start shopping at a better value supermarket. Cheaper food doesn’t mean losing out on taste!


Claim an income tax refund

Patient in hospital bed

If you’ve had to stop working due to long-term illness, or have reduced hours because of it, you might be able to get a refund of some of the income tax you’ve paid.

It’s worth contacting HMRC to check if you’re entitled to some money back.


Consider ways to increase your income

Calculator

We’re not talking about getting another job or going back to work when you’re not ready, because your health must come first. If you’re off work long-term because of your illness, or have a low income as a result, there may be some benefits you’re entitled to.

Use the StepChange benefits calculator to check what you could be missing, and look into any pensions, savings or investments you might have. This’ll help to make sure you’ve got as much money coming in as possible.


Try reducing your rent or mortgage payments

Unhappy man such in hospital

If you’re on a low income and renting, you can apply for a council tax discount. If you’ve got a mortgage, contact your lender or insurance provider to see if you have insurance in place that covers your payments while you’re ill.

You might have mortgage payment protection, critical illness cover, or income protection insurance to help you cover payments. However, bear in mind that any insurance pay-out could affect state benefit claims you make.


Get free advice to deal with debt

If you’re struggling to pay your bills, use the Stepchange online Debt Remedy tool here for advice and practical solutions to deal with your debt, or give their advisors a call.

They will talk through your finances and give you free and impartial debt advice, as well as recommend a debt solution tailored to your situation.

Also, sign up to our free debt help emails here. They will support you as you work to pay off your debts and get better.


six_magpie

Sign Up – Newsletter

The post How to deal with debt with a long-term illness appeared first on MoneyMagpie.

Original source: https://www.moneymagpie.com/make-money/how-to-deal-with-debt-with-a-long-term-illness

Best Canadian Credit Cards for Small Business Owners in 2024

Home Business Magazine Online

Good financial management is key to any business, and as a small business owner here in Canada, one of the best tools you can use is a credit card just right for a small business. A credit card that is right for you will help you track expenses, earn rewards, and even give you useful perks like insurance and purchase protection.

In this post, we review the best Canadian credit cards in 2024 for the small business owner. No matter what your needs—as they pertain to cash back, travel rewards, or low interest—there’s a card for you.

Why Choose a Business Credit Card?

Before we get into specific cards, there’s a prior question: Why should you choose a business credit card rather than a personal one? Business credit cards are created with the business owner in mind, so features range from higher credit limits and more lucrative rewards programs to expense management tools that will help keep your business finances on track.

In addition, having a business credit card helps you keep both your personal and business expenses separate, which is very important from a bookkeeping standpoint, for tax purposes, etc. Many business credit cards offer employee cards with customizable spending limits to give you control over how your employees spend company funds.

Top Canadian Credit Cards for Small Business Owners

1. American Express Business Edge Card

The American Express Business Edge Card is a great option for small business owners who want to earn rewards on everyday purchases. This card offers:

  • 3x Membership Rewards points on eligible business purchases, including office supplies, electronics, and dining.
  • 1x point on all other purchases.
  • Welcome bonus of 30,000 points when you spend $5,000 in the first three months.
  • Annual fee: $99.

You can redeem the points you earn for travel, gift cards, or statement credits. This card also offers purchase protection and extended warranty protection, which can be useful to small business owners who need to buy equipment and supplies regularly.

2. BMO World Elite Business Mastercard

If travel rewards are a priority, the BMO World Elite Business Mastercard might be the right choice for you. With this card, you can earn:

  • 3 BMO Rewards points for every dollar spent on travel, dining, and entertainment.
  • 1.5 points on all other purchases.
  • Welcome bonus of 70,000 points (worth $500 in travel) after spending $5,000 in the first three months.
  • Annual fee: $149.

This card also entitles the cardholder to full travel insurance, which includes trip cancellation and interruption insurance, among others, not leaving out the much-needed car rental insurance. Irrespective of which part of the world you are flying from to the airport, free membership to Mastercard Airport Experiences is being offered by LoungeKey, giving you an opportunity in some of the 1,000 airport lounges spread throughout the world.

3. RBC Avion Visa Infinite Business

The RBC Avion Visa Infinite Business card is designed for business owners who value flexibility in their rewards. Key features include:

  • 1.25 RBC Rewards points for every dollar spent on eligible purchases.
  • Welcome bonus of 25,000 points upon approval.
  • Annual fee: $175.

Points can be redeemed for a wide range of options, including travel, merchandise, and even paying down your credit card balance. This card also offers valuable business tools, such as detailed expense tracking and the ability to set spending limits for employee cards.

4. Scotiabank Passport Visa Infinite Business Card

For business owners who frequently travel abroad, the Scotiabank Passport Visa Infinite Business Card is an excellent choice due to its no foreign transaction fees. Key benefits include:

  • 1.5 Scotia Rewards points for every dollar spent on eligible purchases.
  • Welcome bonus of 35,000 points when you spend $5,000 in the first three months.
  • Annual fee: $199.

In that regard, this card comes with full travel insurance, airport lounges, and foreign transaction fees, which may save you quite a sum if you travel internationally for business.

5. CIBC Aventura Visa Infinite Business Card

The CIBC Aventura Visa Infinite Business Card is another strong option for small business owners, particularly those who want flexible travel rewards. Features include:

  • Two points for every dollar spent on travel through the CIBC Rewards Centre.
  • 1.5 points on eligible gas, dining, and daily transportation purchases.
  • One point on all other purchases.
  • Welcome bonus of up to 50,000 points.
  • Annual fee: $180.

This card also offers travel insurance, purchase protection, and an easy-to-use expense management tool, making it a comprehensive option for business owners.

Choosing the Right Credit Card for Your Business

Deciding which kind of credit card to use for the business can be a want and a need-based decision. Your decision can be based on the factors below:

Spending habits: If many trips are made, a business credit card with good travel rewards plus insurance would be very appropriate. If office expenses are high due to many employees, get one with extra points or cash back in case you purchase office supplies.

Rewards program: Choose between cash back, travel rewards, or points and what those points can really go toward. Some cards are more flexible and free.

Annual fee: Balance the rewards with paying an annual fee. Some annual fee cards are worth it for the perks that accompany them.

Conclusion

The best small-business credit cards in Canada will offer a mix of rewards, benefits, and tools that enable you to manage your finances better. You are looking to rack up travel rewards, save on regular business expenses, or provide additional perks like insurance coverage, and there is a card to fit your needs.

But with the right credit card already selected, not only can you streamline your expense management, but you can also access the rewards and benefits that make growing your business easy. Just remember to consider the unique needs and spending habits of your business before concluding. With the right card in hand, you’ll have a tool that will help crush the financial demands associated with running a successful small business.


About Author

Abid Salahi is the Co-founder of FinlyWealth and the creator of the Finly Credit Card comparison site. He is passionate about personal finance and empowering Canadians to achieve their financial goals through personalized credit card recommendations.

The post Best Canadian Credit Cards for Small Business Owners in 2024 appeared first on Home Business Magazine.

Original source: https://homebusinessmag.com/money/personal-finance/best-canadian-credit-cards-for-small-business-owners-in-2024/
New Google tools to boost first-party data strategies

Google is rolling out two new features to help you navigate the evolving digital privacy landscape and strengthen first-party data strategies.

Why we care. Despite Google deciding to roll back on its plans to remove third-party cookies, with privacy regulations still in place, first-party data has become crucial. These tools is intended to help you simplify data collection and management while respecting user privacy.

Driving the news. Google announced Tag Diagnostics and a new consent management setup, both designed to streamline first-party data collection and utilization.

Details. The new offerings include:

Tag Diagnostics:

  • Provides at-a-glance view of account health.
  • Alerts users to potential measurement issues.
  • Offers guidance on fixing problemsAvailable in Google Tag Manager, Google Ads, and Google Analytics.

Integrated Consent Management Platform (CMP) setup:

  • Streamlines consent banner creation and consent mode implementation.
  • Works within Google Ads, Analytics, and Tag Manager interfaces.
  • Integrates with several CMP partners, including consent manager, Cookiebot, iubenda, and Usercentrics.

What’s next: Google plans to continue adding new diagnostics capabilities and investing in first-party data solutions as the industry evolves.

Bottom line. As digital advertising faces a privacy-driven shift, Google is positioning itself as a key enabler of first-party data strategies for advertisers.

Original source: https://searchengineland.com/new-google-tools-first-party-data-strategies-446107

Best Canadian Credit Cards for Small Business Owners in 2024

Home Business Magazine Online

Good financial management is key to any business, and as a small business owner here in Canada, one of the best tools you can use is a credit card just right for a small business. A credit card that is right for you will help you track expenses, earn rewards, and even give you useful perks like insurance and purchase protection.

In this post, we review the best Canadian credit cards in 2024 for the small business owner. No matter what your needs—as they pertain to cash back, travel rewards, or low interest—there’s a card for you.

Why Choose a Business Credit Card?

Before we get into specific cards, there’s a prior question: Why should you choose a business credit card rather than a personal one? Business credit cards are created with the business owner in mind, so features range from higher credit limits and more lucrative rewards programs to expense management tools that will help keep your business finances on track.

In addition, having a business credit card helps you keep both your personal and business expenses separate, which is very important from a bookkeeping standpoint, for tax purposes, etc. Many business credit cards offer employee cards with customizable spending limits to give you control over how your employees spend company funds.

Top Canadian Credit Cards for Small Business Owners

1. American Express Business Edge Card

The American Express Business Edge Card is a great option for small business owners who want to earn rewards on everyday purchases. This card offers:

  • 3x Membership Rewards points on eligible business purchases, including office supplies, electronics, and dining.
  • 1x point on all other purchases.
  • Welcome bonus of 30,000 points when you spend $5,000 in the first three months.
  • Annual fee: $99.

You can redeem the points you earn for travel, gift cards, or statement credits. This card also offers purchase protection and extended warranty protection, which can be useful to small business owners who need to buy equipment and supplies regularly.

2. BMO World Elite Business Mastercard

If travel rewards are a priority, the BMO World Elite Business Mastercard might be the right choice for you. With this card, you can earn:

  • 3 BMO Rewards points for every dollar spent on travel, dining, and entertainment.
  • 1.5 points on all other purchases.
  • Welcome bonus of 70,000 points (worth $500 in travel) after spending $5,000 in the first three months.
  • Annual fee: $149.

This card also entitles the cardholder to full travel insurance, which includes trip cancellation and interruption insurance, among others, not leaving out the much-needed car rental insurance. Irrespective of which part of the world you are flying from to the airport, free membership to Mastercard Airport Experiences is being offered by LoungeKey, giving you an opportunity in some of the 1,000 airport lounges spread throughout the world.

3. RBC Avion Visa Infinite Business

The RBC Avion Visa Infinite Business card is designed for business owners who value flexibility in their rewards. Key features include:

  • 1.25 RBC Rewards points for every dollar spent on eligible purchases.
  • Welcome bonus of 25,000 points upon approval.
  • Annual fee: $175.

Points can be redeemed for a wide range of options, including travel, merchandise, and even paying down your credit card balance. This card also offers valuable business tools, such as detailed expense tracking and the ability to set spending limits for employee cards.

4. Scotiabank Passport Visa Infinite Business Card

For business owners who frequently travel abroad, the Scotiabank Passport Visa Infinite Business Card is an excellent choice due to its no foreign transaction fees. Key benefits include:

  • 1.5 Scotia Rewards points for every dollar spent on eligible purchases.
  • Welcome bonus of 35,000 points when you spend $5,000 in the first three months.
  • Annual fee: $199.

In that regard, this card comes with full travel insurance, airport lounges, and foreign transaction fees, which may save you quite a sum if you travel internationally for business.

5. CIBC Aventura Visa Infinite Business Card

The CIBC Aventura Visa Infinite Business Card is another strong option for small business owners, particularly those who want flexible travel rewards. Features include:

  • Two points for every dollar spent on travel through the CIBC Rewards Centre.
  • 1.5 points on eligible gas, dining, and daily transportation purchases.
  • One point on all other purchases.
  • Welcome bonus of up to 50,000 points.
  • Annual fee: $180.

This card also offers travel insurance, purchase protection, and an easy-to-use expense management tool, making it a comprehensive option for business owners.

Choosing the Right Credit Card for Your Business

Deciding which kind of credit card to use for the business can be a want and a need-based decision. Your decision can be based on the factors below:

Spending habits: If many trips are made, a business credit card with good travel rewards plus insurance would be very appropriate. If office expenses are high due to many employees, get one with extra points or cash back in case you purchase office supplies.

Rewards program: Choose between cash back, travel rewards, or points and what those points can really go toward. Some cards are more flexible and free.

Annual fee: Balance the rewards with paying an annual fee. Some annual fee cards are worth it for the perks that accompany them.

Conclusion

The best small-business credit cards in Canada will offer a mix of rewards, benefits, and tools that enable you to manage your finances better. You are looking to rack up travel rewards, save on regular business expenses, or provide additional perks like insurance coverage, and there is a card to fit your needs.

But with the right credit card already selected, not only can you streamline your expense management, but you can also access the rewards and benefits that make growing your business easy. Just remember to consider the unique needs and spending habits of your business before concluding. With the right card in hand, you’ll have a tool that will help crush the financial demands associated with running a successful small business.


About Author

Abid Salahi is the Co-founder of FinlyWealth and the creator of the Finly Credit Card comparison site. He is passionate about personal finance and empowering Canadians to achieve their financial goals through personalized credit card recommendations.

The post Best Canadian Credit Cards for Small Business Owners in 2024 appeared first on Home Business Magazine.

Original source: https://homebusinessmag.com/money/personal-finance/best-canadian-credit-cards-for-small-business-owners-in-2024/
Best Canadian Credit Cards for Small Business Owners in 2024

Home Business Magazine Online

Good financial management is key to any business, and as a small business owner here in Canada, one of the best tools you can use is a credit card just right for a small business. A credit card that is right for you will help you track expenses, earn rewards, and even give you useful perks like insurance and purchase protection.

In this post, we review the best Canadian credit cards in 2024 for the small business owner. No matter what your needs—as they pertain to cash back, travel rewards, or low interest—there’s a card for you.

Why Choose a Business Credit Card?

Before we get into specific cards, there’s a prior question: Why should you choose a business credit card rather than a personal one? Business credit cards are created with the business owner in mind, so features range from higher credit limits and more lucrative rewards programs to expense management tools that will help keep your business finances on track.

In addition, having a business credit card helps you keep both your personal and business expenses separate, which is very important from a bookkeeping standpoint, for tax purposes, etc. Many business credit cards offer employee cards with customizable spending limits to give you control over how your employees spend company funds.

Top Canadian Credit Cards for Small Business Owners

1. American Express Business Edge Card

The American Express Business Edge Card is a great option for small business owners who want to earn rewards on everyday purchases. This card offers:

  • 3x Membership Rewards points on eligible business purchases, including office supplies, electronics, and dining.
  • 1x point on all other purchases.
  • Welcome bonus of 30,000 points when you spend $5,000 in the first three months.
  • Annual fee: $99.

You can redeem the points you earn for travel, gift cards, or statement credits. This card also offers purchase protection and extended warranty protection, which can be useful to small business owners who need to buy equipment and supplies regularly.

2. BMO World Elite Business Mastercard

If travel rewards are a priority, the BMO World Elite Business Mastercard might be the right choice for you. With this card, you can earn:

  • 3 BMO Rewards points for every dollar spent on travel, dining, and entertainment.
  • 1.5 points on all other purchases.
  • Welcome bonus of 70,000 points (worth $500 in travel) after spending $5,000 in the first three months.
  • Annual fee: $149.

This card also entitles the cardholder to full travel insurance, which includes trip cancellation and interruption insurance, among others, not leaving out the much-needed car rental insurance. Irrespective of which part of the world you are flying from to the airport, free membership to Mastercard Airport Experiences is being offered by LoungeKey, giving you an opportunity in some of the 1,000 airport lounges spread throughout the world.

3. RBC Avion Visa Infinite Business

The RBC Avion Visa Infinite Business card is designed for business owners who value flexibility in their rewards. Key features include:

  • 1.25 RBC Rewards points for every dollar spent on eligible purchases.
  • Welcome bonus of 25,000 points upon approval.
  • Annual fee: $175.

Points can be redeemed for a wide range of options, including travel, merchandise, and even paying down your credit card balance. This card also offers valuable business tools, such as detailed expense tracking and the ability to set spending limits for employee cards.

4. Scotiabank Passport Visa Infinite Business Card

For business owners who frequently travel abroad, the Scotiabank Passport Visa Infinite Business Card is an excellent choice due to its no foreign transaction fees. Key benefits include:

  • 1.5 Scotia Rewards points for every dollar spent on eligible purchases.
  • Welcome bonus of 35,000 points when you spend $5,000 in the first three months.
  • Annual fee: $199.

In that regard, this card comes with full travel insurance, airport lounges, and foreign transaction fees, which may save you quite a sum if you travel internationally for business.

5. CIBC Aventura Visa Infinite Business Card

The CIBC Aventura Visa Infinite Business Card is another strong option for small business owners, particularly those who want flexible travel rewards. Features include:

  • Two points for every dollar spent on travel through the CIBC Rewards Centre.
  • 1.5 points on eligible gas, dining, and daily transportation purchases.
  • One point on all other purchases.
  • Welcome bonus of up to 50,000 points.
  • Annual fee: $180.

This card also offers travel insurance, purchase protection, and an easy-to-use expense management tool, making it a comprehensive option for business owners.

Choosing the Right Credit Card for Your Business

Deciding which kind of credit card to use for the business can be a want and a need-based decision. Your decision can be based on the factors below:

Spending habits: If many trips are made, a business credit card with good travel rewards plus insurance would be very appropriate. If office expenses are high due to many employees, get one with extra points or cash back in case you purchase office supplies.

Rewards program: Choose between cash back, travel rewards, or points and what those points can really go toward. Some cards are more flexible and free.

Annual fee: Balance the rewards with paying an annual fee. Some annual fee cards are worth it for the perks that accompany them.

Conclusion

The best small-business credit cards in Canada will offer a mix of rewards, benefits, and tools that enable you to manage your finances better. You are looking to rack up travel rewards, save on regular business expenses, or provide additional perks like insurance coverage, and there is a card to fit your needs.

But with the right credit card already selected, not only can you streamline your expense management, but you can also access the rewards and benefits that make growing your business easy. Just remember to consider the unique needs and spending habits of your business before concluding. With the right card in hand, you’ll have a tool that will help crush the financial demands associated with running a successful small business.


About Author

Abid Salahi is the Co-founder of FinlyWealth and the creator of the Finly Credit Card comparison site. He is passionate about personal finance and empowering Canadians to achieve their financial goals through personalized credit card recommendations.

The post Best Canadian Credit Cards for Small Business Owners in 2024 appeared first on Home Business Magazine.

Original source: https://homebusinessmag.com/money/personal-finance/best-canadian-credit-cards-for-small-business-owners-in-2024/